
Understanding the lifetime cap for residential care
If you or a loved one are entering residential aged care you might be asked to contribute towards this care through a Non-Clinical Care Contribution (NCCC). While this contribution is subject to a lifetime cap, we have seen some confusion — particularly around how the time-based cap works.
“Aged care funding rules can feel complex, especially when families are already navigating a significant life transition. Understanding how the lifetime cap works can help people plan ahead and make decisions with greater confidence.”
— Andrew Wem, Aged Care Specialist at Navwealth
How does the lifetime cap work?
Paying for the cost of your care is split between you and the government. Your share is payable as Non-Clinical Care Contribution (NCCC), but a limit applies to how much you will pay over your lifetime.
This NCCC lifetime cap has two components:
- A dollar cap (currently $135,318.69)
- A time-based cap of 1,460 days (equivalent to four years)
Importantly, the NCCC stops permanently when either of these caps is reached -whichever comes first.
It’s also important to understand what the cap does not apply to. The lifetime cap does not cover other residential care fees, such as the hotelling contribution, basic daily fee or accommodation costs. However, the dollar cap does include contributions previously paid under a Home Care Package (as an income-tested fee) or under Support at Home. This means earlier contributions at home might reduce the remaining dollar cap once you enter residential care.
The time-based cap, however, only applies to days when the NCCC is paid in residential care. Time spent receiving care at home does not count toward the 1,460-day limit. Each individual day that the NCCC is payable counts toward this total.
If you were already in care before 1 November 2025 (or enter now under the grandfathering rules) the NCCC does not apply. If you are in this group, you might instead be asked to pay a means-tested fee and with just a lower dollar lifetime cap of $84,571.66. The time-based cap does not apply here.
Why timing matters
The four-year cap is not always four calendar years from the date you enter care. It only counts periods when the NCCC is actually payable.
For example, if someone enters care but is not immediately required to pay the NCCC due to lower assessable assets, the time-based cap does not begin until the first day the NCCC becomes payable. If the NCCC is payable continuously from that point, it would cease 1,460 days later (or earlier if the dollar cap is reached first).
Making the right choice
Because everyone’s financial situation is different, careful modelling is essential to understand how long the NCCC may apply, when the cap is likely to be reached and what this means for your affordability and cashflow planning.
Personalised advice can help ensure you understand your obligations and avoid unexpected costs.
Final thought
Aged care decisions are rarely just financial — they’re deeply personal. Understanding how rules like the lifetime cap work can provide clarity at a time when families are often navigating complex choices.
“When families have the right information and support early, it removes a lot of the uncertainty around aged care decisions. The goal is always to help people feel informed, prepared and confident about the path ahead.”
— Andrew Wem, Aged Care Specialist at Navwealth
If you or someone you care about is starting to explore residential aged care, a conversation with an experienced adviser can make all the difference.
The Navwealth aged care advice team is here to help you understand your options and plan with clarity and confidence.
💬 Reach out to our team to start the conversation.
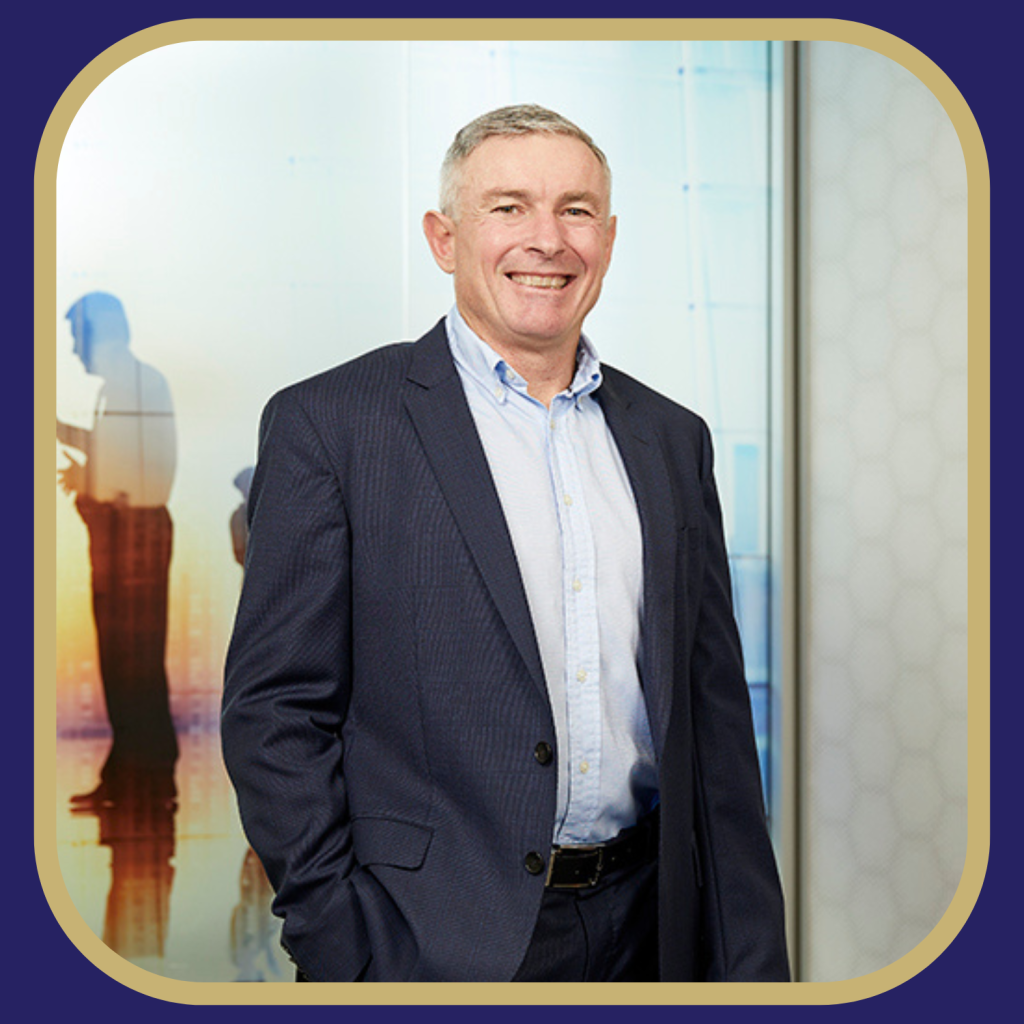
Meet Andrew Wem. A financial Adviser for over 25 years, Andrew brings a wealth of experience around issues that help bring solutions that others would have never thought about. Helping people through divorce, death, starting a family, or moving a loved one into aged care—you need to have dealt with these things to know how to help others through them. He is an Aged Care Specialist Adviser.
Contact Andrew here to discuss how he can help you.