
Understanding RADs: A clearer path to funding aged care
When moving into residential aged care, you might find the thought of paying a large lump sum to be confronting, but don’t be afraid of a RAD. The full name of this payment – a Refundable Accommodation Deposit – provides a clue why you should not be afraid.
“A Refundable Accommodation Deposit can feel like a big decision at first, but when you understand how it works, it often provides both financial clarity and peace of mind. It’s about choosing the option that best supports your lifestyle, your family, and your long-term security.”
— Andrew Wem, Aged Care Specialist at Navwealth
When you move into residential care, you are effectively moving into a new home. And just like any move to a new home, there is a cost to secure your accommodation – you either need to find a lump sum to buy the accommodation or create cashflow to pay rent.
With a move into care, one of the first expenses you will face is the cost of your room. This is likely to be quoted as a lump sum but you have the choice to either pay the lump sum (called a Refundable Accommodation Deposit – RAD) or turn it into a daily fee (called a Daily Accommodation Payment – DAP). You can also choose to pay a part lump sum and part daily fee.
While many people hesitate at the idea of a lump sum, paying a RAD can often be a financially sound choice, if you have the means to do so.
Four things to know about RADs
Firstly, the RAD is mostly refundable when you leave care or pass away. The provider can only deduct and keep a small retention amount (up to 2% each month for the first five years) and any outstanding fees. The majority of your money remains as part of your estate.
Example:
Carol pays a $750,000 RAD. If she passes away two years later, the care provider will have deducted $29,432 in retention amounts, leaving $720,568 to be refunded to her estate.
The refund of the RAD is guaranteed by the Federal Government. So, the second thing to know is that even if the aged care provider experiences financial difficulty, your deposit is protected.
Thirdly, if you choose not to pay a RAD, you’ll pay the Daily Accommodation Payment (DAP) instead. This is effectively interest (currently at 7.96% per annum) on the unpaid amount. And none of this interest paid is refundable.
Example:
If Carol opts to pay just the DAP, she would pay $163.56 per day ($59,700 per year) as “rent”. This stops when she passes away, but none of the DAP paid is refundable.
And fourthly, the RAD paid is exempt when calculating age pension entitlements. This can potentially increase your entitlements and help offset lost investment income.
Review your whole situation
Deciding how to structure your aged care costs, whether through a RAD, DAP, or a combination of both, is about more than just the numbers. It’s about understanding how each option supports your cashflow, your entitlements, and your overall financial wellbeing.
With so many moving parts, it’s natural to feel uncertain. But with the right guidance, these decisions can become clearer and far less overwhelming.
If you’re starting to explore your options or simply want to understand what might work best for your situation, our team is here to help.
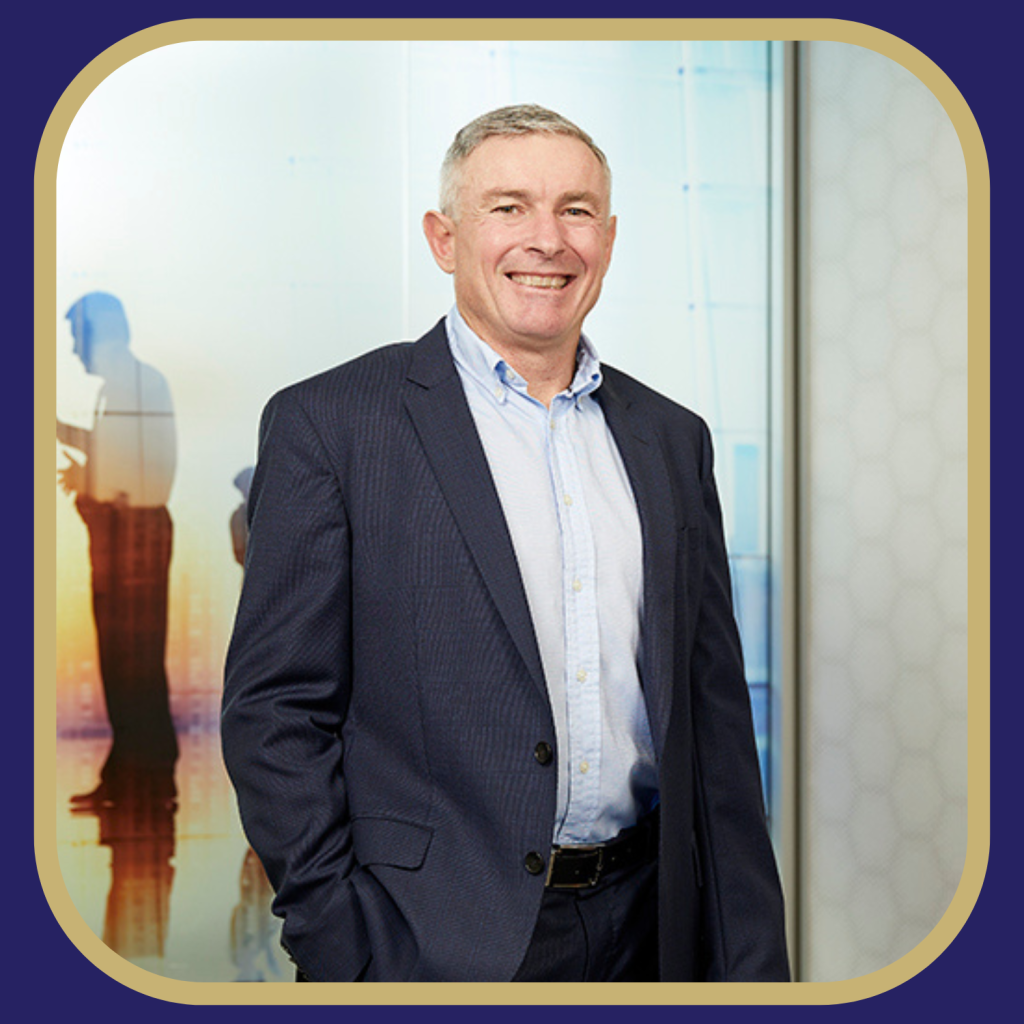
Meet Andrew Wem. A financial Adviser for over 25 years, Andrew brings a wealth of experience around issues that help bring solutions that others would have never thought about. Helping people through divorce, death, starting a family, or moving a loved one into aged care—you need to have dealt with these things to know how to help others through them. He is an Aged Care Specialist Adviser.
Contact Andrew here to discuss how he can help you.